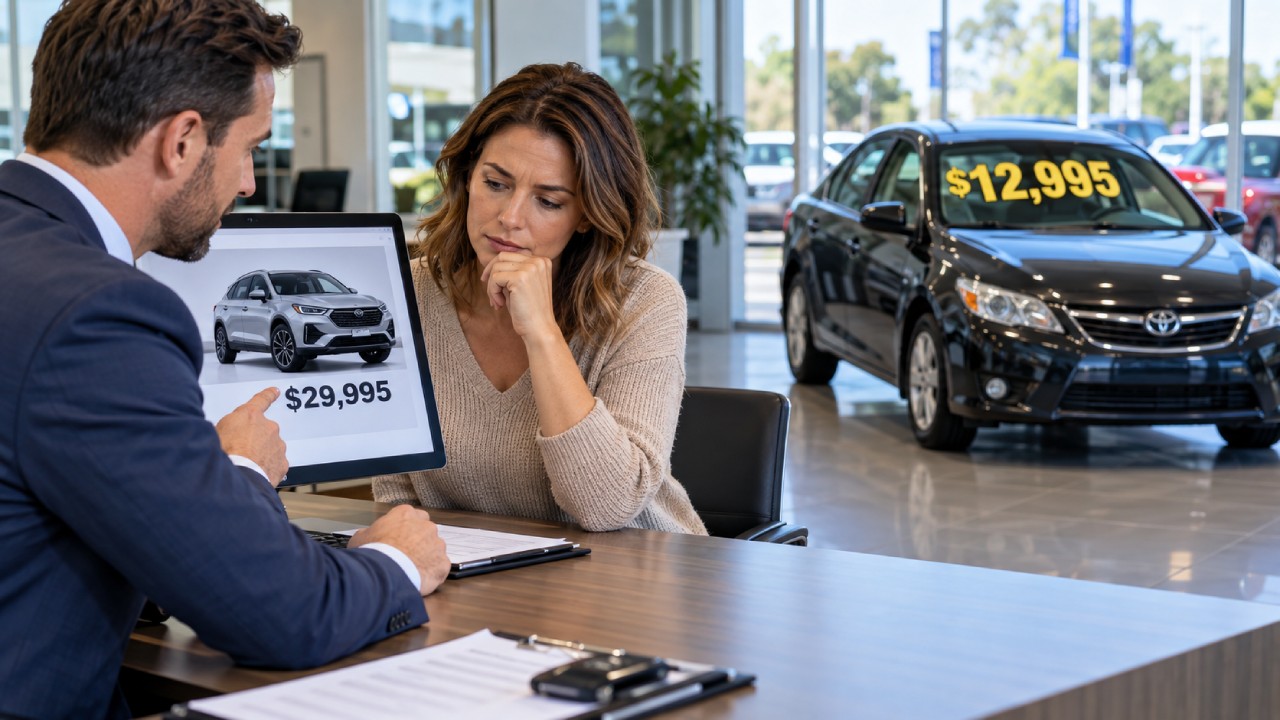
If your sales desk keeps hearing that the payment is too high, audit the cheaper choices it can actually offer. The question is whether your wholesale decisions have removed vehicles that could have served those buyers. An older car does not automatically solve the payment problem, since a lower price can come with a higher APR; Experian reported U.S. averages of 6.35% for new-vehicle loans and 11.19% for used-vehicle loans in Q2 2026.
Consider a made-up deal at a U.S. dealership. A buyer cannot afford a $29,000 SUV and asks, “What do you have for less?” A sedan with an expected $12,500 retail price has already gone to auction after a $2,500 recon estimate. Changing trim or extending the loan cannot make that sedan available again.
You authorize wholesale exits to protect the store from repair exposure and money tied up in questionable inventory. That recon bill may justify moving one vehicle. Applying the same cutoff without examining each car could remove your entire lower-priced selection.
1. Count vehicles you could deliver today
Take a dated inventory snapshot and count available, retail-ready vehicles priced below $15,000. Treat $15,000 as an audit threshold, not a universal affordability line. A store serving a different market should use the price point that represents a meaningful step-down for its own buyers.
Exclude sold units and cars awaiting repairs. Keep pending recon units in a separate column so tomorrow's possible inventory does not inflate today's selection.
The count is only the starting point. The more important question is what happened to the lower-priced vehicles your store already acquired. Put most of your effort into reviewing the wholesale decisions in step 3, where you can uncover an automatic exclusion.
2. Separate a low price from a workable payment
Have F&I identify which counted vehicles fit at least one available lender program. Record the permitted term and indicative APR, and ask whether older collateral would require a shorter term or higher rate. Vehicle eligibility is not borrower approval.
For example, Bank of America excludes vehicles more than 10 calendar years old and vehicles with at least 125,000 miles. It also identifies term and loan-to-value restrictions. Those are one lender's limits, not universal wholesale cutoffs.
Navy Federal Credit Union lists model year and mileage among the factors affecting its APR. Use your actual lender programs rather than assuming every inexpensive vehicle supports the same payment structure.
The Consumer Financial Protection Bureau explains that extending repayment can lower monthly payments while increasing total interest. For this audit, price the complete deal with applicable taxes and fees, then account for down payment and any trade balance. Keep cash-only inventory visible, but separate from options for buyers who need financing.
3. Reconstruct the last 90 days of wholesale decisions
Pull every trade you wholesaled during the preceding 90 days. Flag vehicles that could plausibly have sold at retail below $15,000 when you made the decision. Do not filter solely by acquisition cost: a low trade allowance does not establish a low retail price.
Create one row per VIN. Record age and mileage, the supported retail estimate, recon evidence and net wholesale proceeds. Attach the appraisal, inspection or repair order, and wholesale settlement where available.
Classify the stated reason for the exit:
- Recon cost: the estimate exceeded what the vehicle could support.
- Mechanical exposure: a diagnosed problem or unresolved condition made retail risk unacceptable.
- Age or mileage policy: the vehicle crossed an internal cutoff.
- Title or history: a documented issue ruled out retail under your standards.
- Expected gross: the projected return failed the store's requirement.
Allow multiple reasons, but identify which one determined the decision. Mark missing support as unknown. “Too much recon” without an estimate is neither proof of a sound exit nor evidence that the car deserved a retail spot.
4. Reopen only files with a credible retail case
Start with policy exclusions that have usable condition evidence. Do not spend the audit trying to rescue cars with documented risks your store cannot responsibly carry.
The Federal Trade Commission cautions that a history report cannot replace an independent mechanical inspection. A clean report alone should not move an undocumented wholesale unit into your candidate column.
Review itemized recon with the service manager. Identify cosmetic work you could reasonably omit, but never make the numbers work by skipping safety work or required repairs. If the condition evidence cannot support a bounded repair estimate, leave the file unresolved.
5. Compare what each exit would leave the store
For plausible candidates, compare expected retail receipts after remaining costs with net wholesale proceeds. Use a supportable selling price, not the highest advertised comparable. Include holding costs through the expected sale date and an allowance for warranty or goodwill comebacks based on your own repair history.
Complete the sedan's comparison with these additional cost assumptions. Retail channel costs cover selling and holding; wholesale channel costs cover transport and auction charges.
| Item | Retail | Wholesale |
|---|---|---|
| Expected selling price | $12,500 | $8,300 |
| Remaining recon | $2,500 | $0 |
| Channel costs | $500 | $300 |
| Expected post-sale repair cost | $600 | $0 |
| Net proceeds before inventory cost | $8,900 | $8,000 |
Retail has a $900 expected advantage, not $900 of total profit. Deduct the same inventory cost from either route to calculate the vehicle's contribution. Do not charge either option again for recon already completed before the decision.
Test the retail estimate against a lower selling price or additional repair work. The expected advantage must justify keeping the vehicle through the selling period and occupying a retail slot. A narrow advantage can still support a wholesale decision.
6. Decide which policy, if any, deserves changing
Separate documented, economically justified exits from vehicles excluded by a blanket rule. Keep unresolved files outside both groups until the evidence supports a conclusion.
If every plausible candidate fails on condition or net return, the audit does not justify retaining cheaper trades. If the candidates lack a realistic financing route, they do not solve this particular problem for payment-dependent buyers. A cash-sale opportunity is a separate decision.
If some candidates pass the condition and economic tests, and F&I identifies workable financing, authorize individual review of the next similar trades. Specify who approves exceptions and when the store will reconsider a retained unit. Do not replace an automatic wholesale rule with an automatic retention quota.
The defensible finding is that some vehicles deserved consideration, not that each wholesale exit cost you a sale. Check deal notes for buyers whose budgets and vehicle requirements actually matched the excluded stock.
Judge the retained vehicles, not just the count
A fuller budget row is not enough to call the change successful. Track actual recon against the estimate and record days to sale. Compare realized contribution with the wholesale alternative documented when you retained the car, including comeback costs as they emerge.
Have the sales desk record whether buyers accepted these alternatives and why they declined them. That distinguishes useful selection from inexpensive inventory that still misses the customer's needs.
Start today with the dated count. Then use the wholesale files to decide whether your store needs a selective exception or should keep making the same exits. Interest rates may remain part of the explanation, but they should not substitute for examining the cars you chose not to offer.